Excerpts from RHB report
Analyst: Shekhar Jaiswal
♦ Keep BUY, new SGD1.25 TP from SGD1.30, 23% upside and 4% 2021F yield. We lower 2020F profit by 19% to account for slower international aviation traffic recovery and weak 1H20 earnings for SPIA.
Its monopolistic position in China and cost-plus business model ensure free cash flow generation. Its stock is trading below its NTA/share of USD0.95 (c.SGD1.30), and at ex-cash 2021F P/E of just 2.6x.. 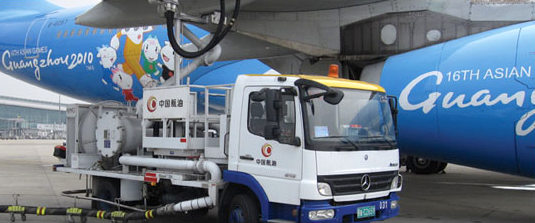 CAO owns a 33% stake in SPIA, the sole supplier of jet fuel for the second largest airport in the PRC – Shanghai Pudong International Airport. Photo: CAO |
||||
♦ Weak 1Q20 earnings. China Aviation Oil reported disappointing 1Q20 net profit of USD10.8m (-59% YOY, -49% QoQ).
This was due to lower attributable profit of USD5.6m (-68% YoY, -58% QoQ) from Shanghai Pudong International Airport Aviation Fuel Supply Co (SPIA), a 33%- owned associate of CAO.
SPIA offers exclusive aircraft refuelling services at Shanghai Pudong International Airport (SPA).
Historically, SPIA has accounted for c.65% of CAO’s PBT. Earnings were also dragged lower by weak international aviation traffic in China.
♦ Lower earnings in the near term. About 20% of CAO’s gross profit is attributable to supply of imported jet fuel to China.
While the cost-plus model for this business ensures that CAO reports profit, earnings growth is linked to China’s international aviation traffic.
Even for SPA, c.40% of aircraft movements at the airport accrue from international traffic.
We now expect international aviation passenger traffic in China and at SPA to start improving only towards end-3Q20 instead of the earlier expectation of end-2Q20.
To account for this, we lower 2020 earnings estimates by 19%. We lower 2021F-2022F estimates by 6-7% as well.
| Domestic recovery |
|
|
♦ Domestic aviation traffic in China is recovering and could still help re-rate the stock. With the spread of COVID-19 infections now under control in China, we believe there is scope for an earlier-than-expected recovery in China’s domestic aviation traffic.
China's aviation regulator (CAAC) noted MoM improvement in aviation traffic.
Passenger numbers rose 7.9% this month as of 21 Apr, and the number of daily flights rose only 1% in April from March.
While this will not support a recovery in CAO’s jet fuel import volume that is dependent on China’s international aviation traffic, SPIA could still report higher jet fuel volumes for 2H20.
| ♦ Valuations undemanding. CAO continues to trade below its net tangible asset value per share of USD0.95 (c.SGD1.30). Its 2021F P/E of 6.8x is below its peers. Our SGD1.25 TP implies 0.9x P/NTA, which is reasonable given the near-term earnings weakness. In addition, a strong net cash position (c.60% of its market cap) should enable CAO to undertake a sizable earnings-accretive acquisition. Its ex-cash 2021F P/E is just 2.6x. |
Full report here.


