|
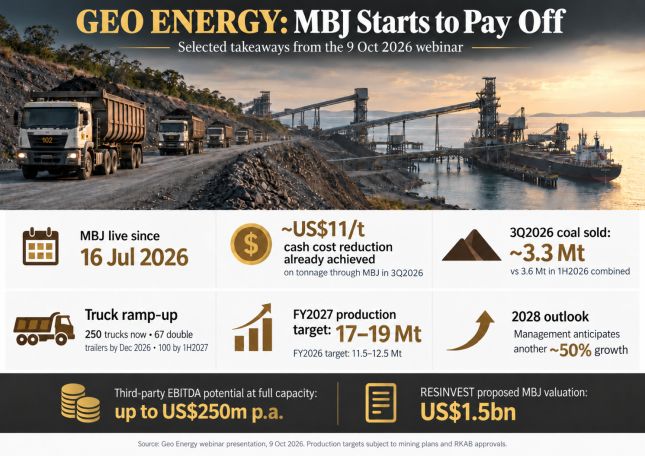
Geo Energy has built the road. Now comes the exciting part — putting it to work and reaping the rewards. Its 92-km coal-hauling road and associated jetty, developed under PT Marga Bara Jaya (MBJ), have been operational since July 2026. And management is thinking big. Strikingly, management anticipates another roughly 50% y-o-y increase in coal volumes in 2028. It is an ambition, not guaranteed output. If achieved, Geo could be looking at a very different scale of operations in just two years. |
| Bigger trucks, then a bigger jetty |
The operational details are becoming more concrete.
• Geo said about 250 smaller trucks, carrying 35–45 tonnes each, are already deployed on MBJ.
• Double-trailer trucks carrying 140 tonnes started being deployed in October.
• Management aims to have about 67 double trailers by Dec 2026 and 100 by 1H2027.
These numbers give investors a concrete idea of the ramp-up.
 There is another important distinction: the road’s capacity is not the same as the entire infrastructure’s capacity.
The Phase 1 jetty, from which coal is loaded onto barges for onward shipment, currently limits throughput to 20–25 million tonnes annually.
Management intends to begin developing Phase 2 during 2027, with construction taking nine to 12 months and operations targeted for early 2028.
That would enable approximately 50 million tonnes of annual infrastructure capacity.
| Choosing the right customers |
MBJ’s attraction extends beyond transporting Geo’s own TRA coal. Nearby miners could become paying road users.
Geo says it has secured binding term sheets covering nine million tonnes of annual third-party haulage.
Management is nevertheless still evaluating prospective customers and negotiating commercial arrangements, including with those counterparties.
Management used the analogy of a landlord choosing reliable tenants: the objective is not simply to fill space, but to select customers capable of paying through coal-market fluctuations.
Third-party usage is expected sometime in 2027. However, no firm revenue figure or start date was supplied.
MBJ has the potential to generate up to US$250 million in annual third-party EBITDA at full capacity (25 million tonnes external capacity), alongside logistics savings on Geo’s own coal.
| Tonnes of savings |
Management also explained the expected savings of more than US$10 per tonne routed through MBJ.
Avoiding external tolls saves US$7–8 per tonne, while more efficient haulage contributes another US$6–7, partly offset by MBJ’s operating and maintenance costs.
Importantly, the benefit is already showing up in its operating costs.
Geo reported achieving ~US$11/tonne of cash cost reduction on tonnage through MBJ in 3Q2026.
Group coal sales totalled about 3.3 million tonnes in 3Q2026, almost matching the 3.6 million tonnes sold in the entire first half.
| Will stronger earnings convince the market? |
Geo's stock price has been volatile, though it's +28% year-to-date. The stock has retreated from its end-Sept level of 62 cents, suggesting that investors are cautious given the market-wide sluggishness.
With coal prices strengthening and production ramping up, Geo should report substantially stronger earnings for 3Q and 4Q2026. That could catalyse a re-rating of the stock.
The benchmark ICI4 coal price now sits ~31% above its 1H2026 average, and forward pricing points to ~US$78/t through the end of 2027.
Management attributed stronger coal prices to rising electricity demand, including from AI and data centres, alongside energy-security concerns arising from the Middle East conflict.
CFO Adam Tan said more expensive gas was also encouraging power producers to reactivate older coal-fired plants.
On 28 Sept, Geo said it expected sales volume and net profit for 3Q2026 to increase significantly against not just 3Q2025, but also each of the first two quarters of 2026.
“As earnings strengthen and with potential investors’ interest in the Group’s core assets, including and not limited to the investment of MBJ by ResInvest, the Board will continue to evaluate future capital allocation through consistent quarterly dividends, active share buybacks and/or special dividends.”
Meanwhile, ResInvest’s proposed investment has reached the legal-documentation stage, with the US$1.5 billion MBJ valuation reiterated. The takeaway? Geo has provided more details of a growth roadmap. |
 See the PowerPoint deck here. See also: GEO ENERGY: Backs Bullish Profit Guidance With Record Buyback—At A Higher Price |


