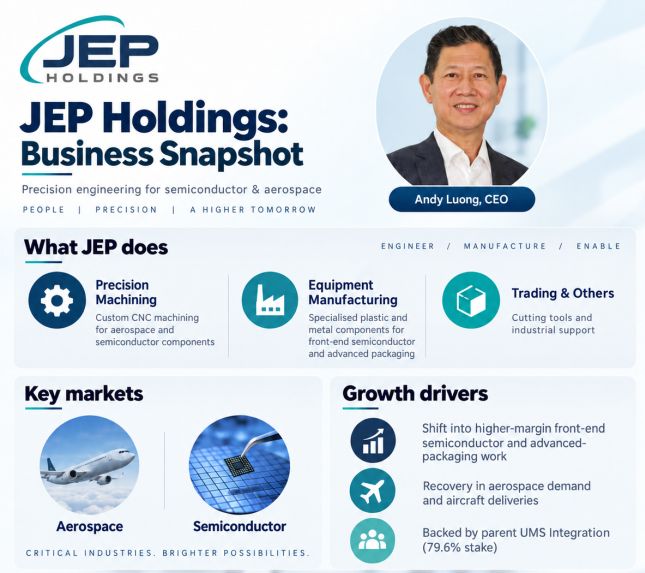
• JEP is increasingly working on high-value front-end semiconductor and advanced-packaging components, just as its aerospace business is also picking up. Read excerpts of his report (BUY, S$0.83 target price with a pretty rich 28x forward P/E) below .... |
Excerpts from Phillip Securities report
Analyst: Ben Yik
▪ JEP is partnering with a major front end semiconductor customer to supply specialised plastic components.
|
|||||
▪ JEP's aerospace business supplies highly specialised and customised aircraft parts, such as engine casings and landing gear components, for widebody aircraft used on long-haul flights.  Ben Yik, analystAerospace revenue rose 37.5% YoY to S$15.8mn in 1H26, driven by stronger widebody aircraft deliveries.
We expect widebody deliveries to rise about 13% CAGR over the next three years as industry supply bottlenecks ease.
▪ We initiate coverage with a BUY recommendation and TP S$0.83.
Our TP is based on 28x FY27e P/E, a 7% discount to peers’ average forward P/E of 30x.
We believe JEP rides on the organic growth of its parent company, UMS Integration.
We estimate about 30% of JEP’s recurring semiconductor metal orders from UMS.
As UMS and JEP’s key semiconductor front end equipment customer raised its expectations for 2026 WFE spend to the be about US$150bn (prev. US$135-140bn), we believe it would drive demand for JEP’s semiconductor revenue.
| Company background |
▪ JEP Holdings Ltd (JEP) is a precision machining and engineering solutions provider listed on SGX Catalist since 2004. It is a subsidiary of UMS Integration.
JEP has over 30 years of operating history and has supplied aerospace components to the global supply chains of leading aircraft engine makers since 1990.
In FY25, revenue mainly came from aerospace (46%) and semiconductor (27%) industry. JEP operates three manufacturing facilities in Singapore and Malaysia (Penang).
| Investment merits |
▪ New orders secured for specialised plastic components in front-end advanced semiconductor packaging.
JEP’s key customer is expanding its manufacturing capabilities in Asia, especially for plastic components used in wet etch, deposition and plating processes for advanced packaging.
JEP increased capex spending by more than 2x YoY to S$20.6mn in FY25 to expand capabilities in Singapore to support production of the specialised plastic components.
We expect mass production of the specialised plastic components to drive FY27e equipment revenue to increase by more than 100% YoY to ~S$50mn.
▪ Aerospace sees stronger demand from aircraft deliveries.
Bottlenecks in aircraft deliveries are easing, and widebody deliveries are expected to increase by 13% CAGR over the next three years.
Boeing increased its 787 Dreamliner production target from 8 to 10 jets monthly by 2026 and expects the first delivery of 777X widebody jet program by 2027e.
We expect higher demand for aircraft parts, such as engine casings and landing gear components, to drive JEP’s aerospace segment.
JEP's semiconductor business (27% of FY25 revenue) benefits from the organic growth of its parent, UMS Integration.
JEP’s aerospace-grade machining can be applied to manufacturing semiconductor parts. |
 See also: UMS: Citi Sees FY2028 Profit at S$136M. That's 33-40% Above DBS, UOBKH Forecasts |

