|
• Microcaps, when they turn a corner, can enjoy strong earnings recoveries. There's one which is attracting some attention --Aedge, whose businesses are unglamorous but serve everyday needs and a broker has just forecast 84% earnings surge in FY2027.
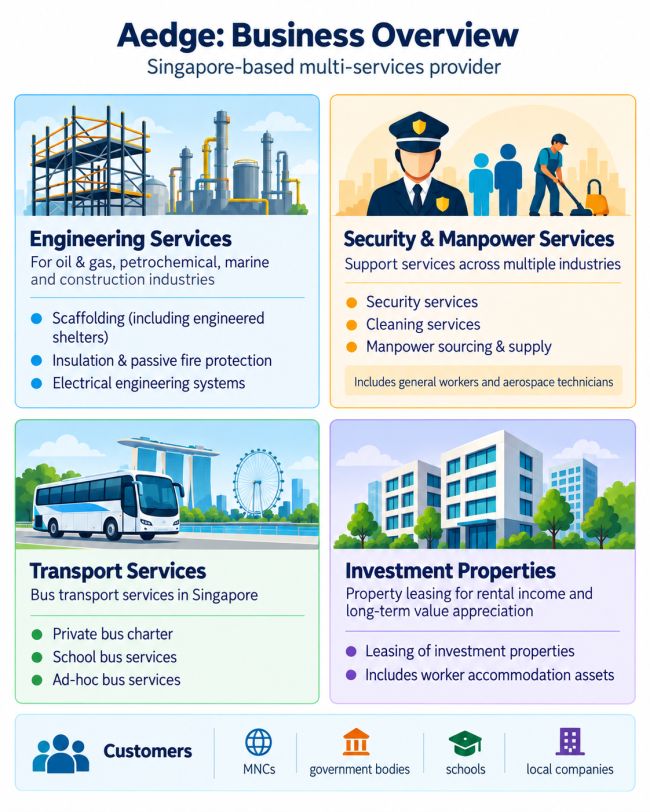
Aedge provides engineering, bus transport, security and manpower services, alongside a growing worker-accommodation business.
• For FY2026 ended 30 June, revenue rose 36.9% to S$38.4 million, while profit attributable to shareholders reached S$2.38 million, reversing a S$650,000 loss. Importantly, gross margin improved from 13.0% to 19.7%.
• Worker accommodation could provide the next leg of growth. Aedge ended FY2026 with 707 operational dormitory beds, up from 299 at the half-year mark.
• The recent $3.5 million share placement drew several well-known funds and investors including Azure Capital, ICH Synergrowth Fund, Lum Chang Creations MD Lim Thiam Hooi and businessman Michael Kum.
And now, Lim & Tan Securities has initiated coverage with a BUY and a 29.5-cent target.
• Read excerpts of its report below .....
|
Excerpts from Lim & Tan Securities report
Analysts: Chan En Jie / Linus Loo
| Riding on 3 big tailwinds |
We initiate a BUY rating on AEDGE GROUP LIMITED with a target price of S$0.295, pegged to a 10.8x P/E on blended FY27F/FY28F EPS.
|
AEDGE
|
|
Share price:
$0.215
|
Target:
$0.295
|
Aedge, with its diversified essential-services platform spanning multiple segments, stands to benefit from three converging tailwinds: a multi-year construction upcycle, sustained foreign-worker demand, and a structural Purpose-Built Dormitory shortage.
After meeting their 2H FY26 guidance, Aedge is on track to recording a better FY27.
This momentum is supported by contract renewals with expanded scope across all service segments.
|
Aedge has completed a successful round of share placements attracting institutions Azure Capital, ICH, as well as strategic investors Lum Chang Creations Mr Lim and hotel and offshore marine tycoon Mr Michael Kum.
Executive Chairman Mr Poh Soon Keng has since bought a further 400,000 shares on-market at c.S$0.21.
| Essential-services tailwinds |
BCA has projected 2026 construction demand at S$47–53bln, among the highest sustained levels on record.
This is anchored by projects like Changi T5, MBS IR2, and the DTL2 and TEL extensions.
Foreign-worker headcount in Construction, Marine & Process stands at c.482,600 and recent MOM policy widened the sectors eligible to hire Work Permit Holders.
The Purpose-Built Dormitory market is running at c.96–97% occupancy with bed rents “markedly higher than pre-pandemic levels”, and the 2030 FEDA deadline is forcing older facilities out of supply.
Aedge is well-positioned to take advantage of these tailwinds as it supplies the labour, transports it, services its workplaces, and increasingly houses it.
Diversified platform and a turn to profitability. Aedge operates four complementary segments guided by an essential-services philosophy: engineering, transport, security & manpower, and investment properties.
They serve a blue-chip client roster spanning government ministries, statutory boards, and major REIT / property owners.
FY26 delivered the first profitable full year after a FY25 investment-cycle year, with operating cash flow of S$5.34mln (vs S$3.82mln FY25).
Segment catalysts in motion. Investment Properties: Beryl House obtained its dormitory licence on 12 May 2026 and has been income producing since May, contributing about 1 month to the full year results, while Carnelian House (219 Kallang Bahru) completed in Jun 2026 and a freehold Geylang option was exercised 20 Jul 2026.
Engineering (FY26 +57.6%) and Transport (+31.8%) are scaling directly into the construction cycle, with management citing “contract renewals with expanded scope and improved margin terms”.
Security & Manpower (GP +68.8% to S$2.5mln) has “onboarded new customers with expanded project requirements”, with cleaning and flex staffing absorbing transitional softness in guarding.
| Supercharged +84% earnings forecasted |
We value Aedge using a relative-valuation approach, comparing Aedge to relevant SGX-listed peers. Applying the peer average forward P/E of 10.8x to a 50/50 blend of FY27F and FY28F EPS (2.74¢) implies a target price of S$0.295, for an upside of +37.2%.
|
Stock price
|
$0.21
|
|
52-week range
|
$0.17-$0.39
|
|
Market cap
|
$38.4 M
|
|
52-week change
|
15% |
|
PE (ttm)
|
13.7
|
|
Dividend yield
|
2.65%
|
|
P/B
|
2.8
|
|
Source: Reuters
|
Although Aedge’s market cap of S$38mln is materially smaller than peers, which range from S$0.24bln (LHN) to S$1.19bln (Centurion), we do not apply a size discount, given its materially faster earnings growth (FY27F EPS +84% against a peer average of 7%).
We also note that EBITDA is a particularly relevant metric for Aedge given that investment properties generate c.S$1.8mln of depreciation, suppressing net profit.
On an EBITDA basis, our FY27F estimate of S$10.3mln implies an EV/EBITDA of approximately 5.6x at the current share price, a c.43% discount to the peer median of 9.8x.
This is a deeper discount than the P/E comparison alone suggests, and one that we regard as the more meaningful expression of the valuation gap.
We initiate a BUY rating on AEDGE GROUP LIMITED with a 12-month target price of S$0.295.
We like Aedge’s 1) contract renewal reflecting sustainable earnings, 2) diversification into investment properties, and 3) complementary business segments amid converging macro tailwinds.
|
 See earlier story: |